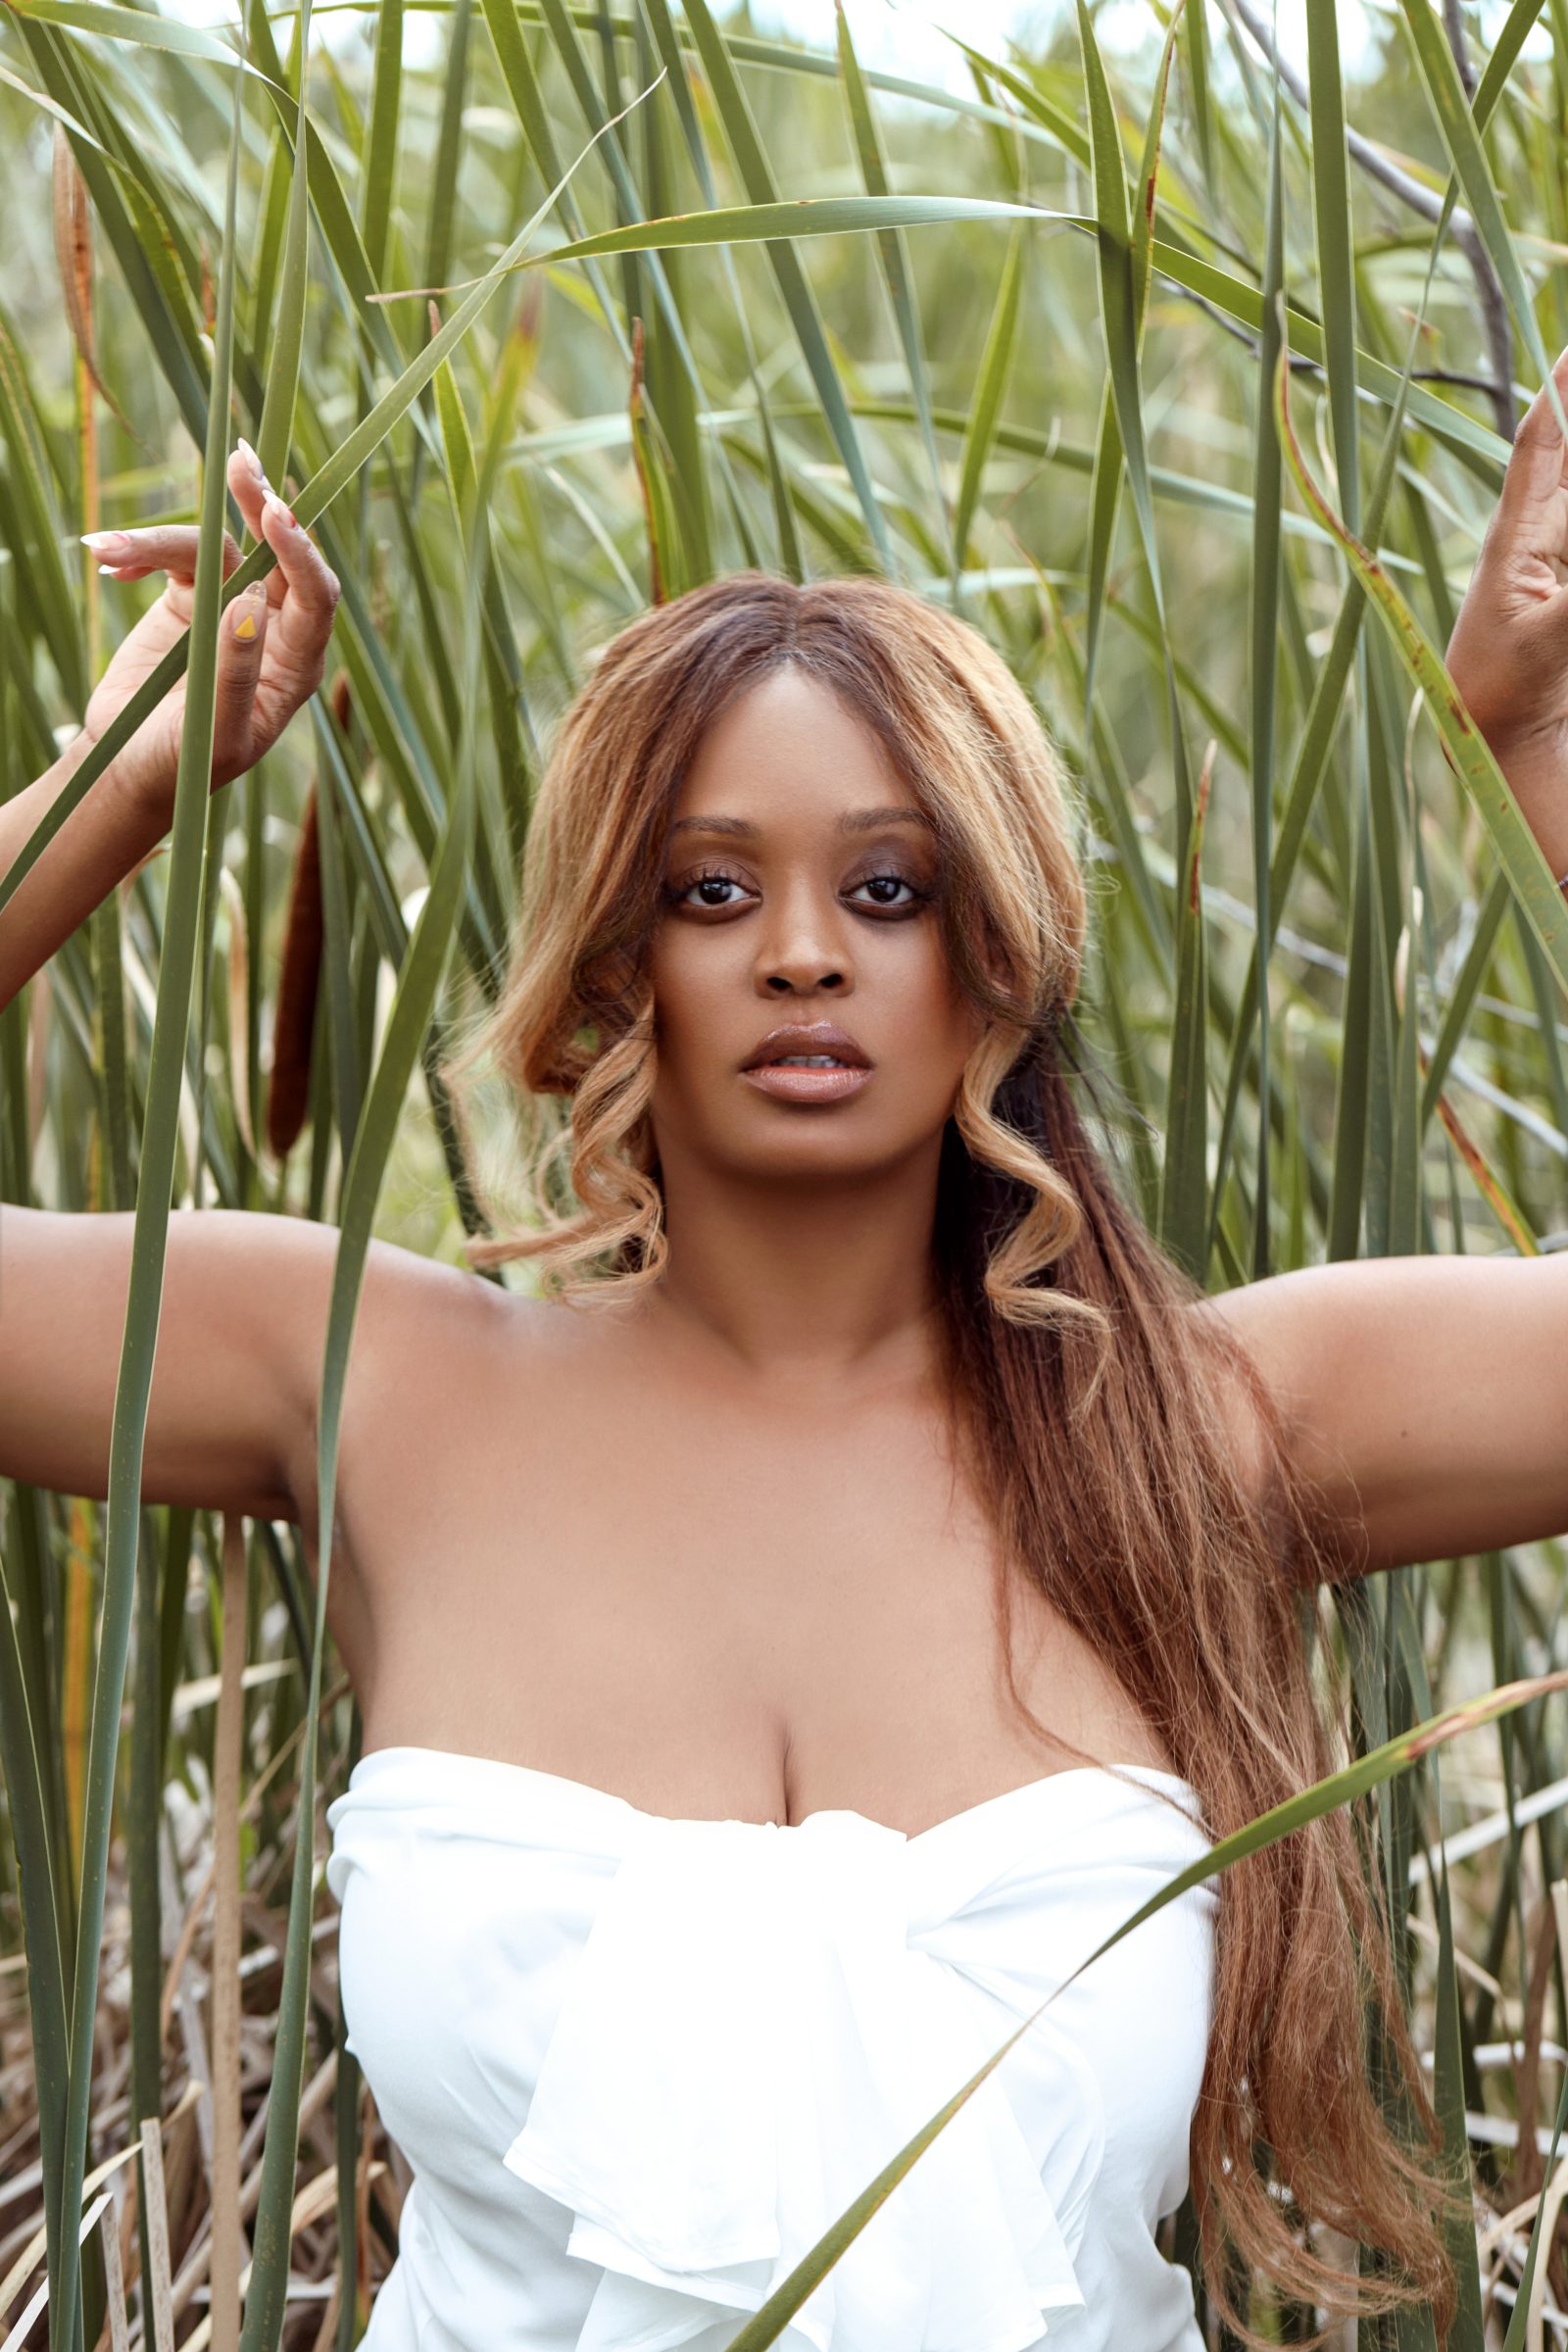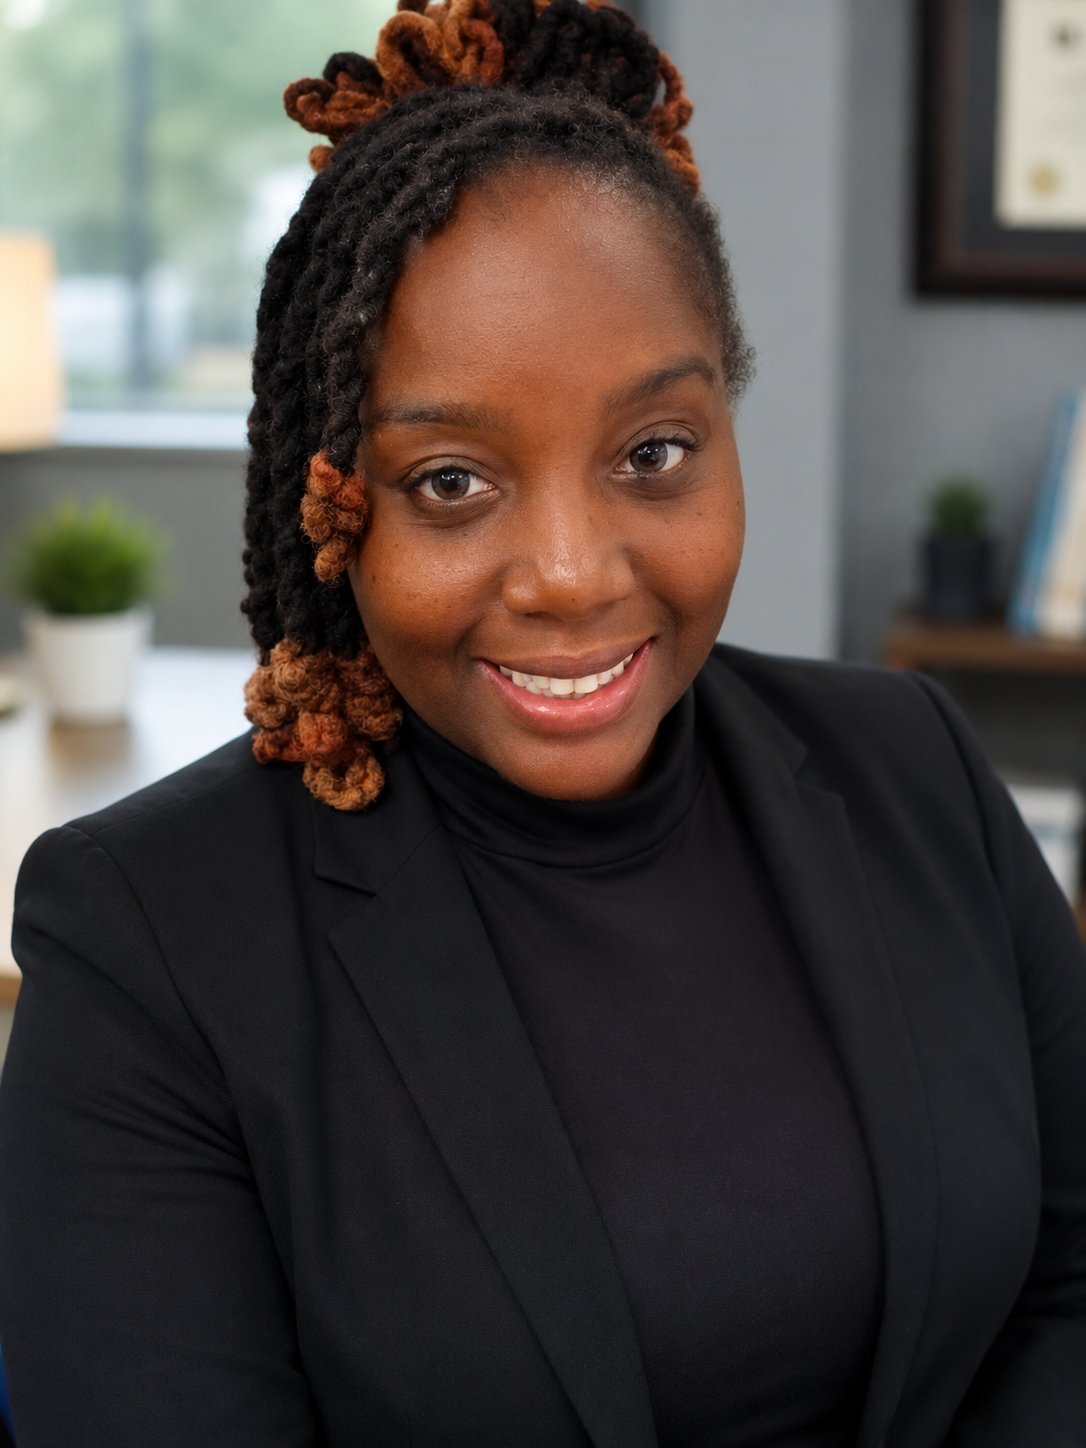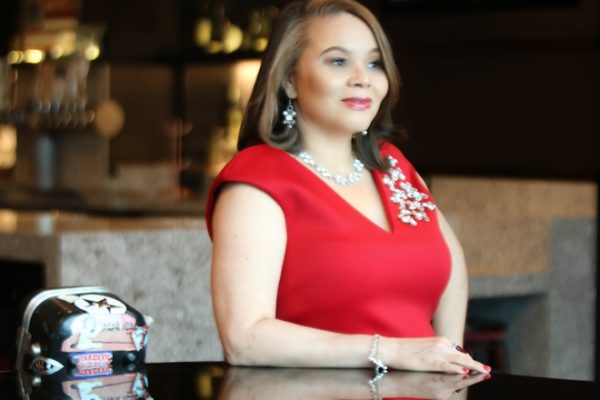
Dr. Cozette M. White is an acclaimed bestselling author, a nationally recognized finance and tax strategist, international speaker and philanthropist. Dr. Cozette helps executives develop and execute viable solutions for delivering solid operating results and profitable long-term growth.
Dr. Cozette is the Founder and CEO of My Financial Home Enterprises, a global financial firm providing comprehensive accounting, tax, and business management services for businesses and individuals. My Financial Home has been featured in Forbes Magazine and named one of The Boss Network’s top 50 companies two years in a row. She strongly believes that successful leaders such as her have a duty to share their knowledge and facilitate the success of others.
Dr. Cozette is the resident “money matters†on Fox40 and her advice has been called upon by CBS This Morning, NBC, ABC, and FOX television stations. She has been featured on Radio One and iHeart radio. She has been coined the “Financial Physician†as a result of her unparalleled ability to diagnose and boost the financial health of organizations and families.
Fancy: How would you describe your swagher? What makes Dr. Cozette, Dr. Cozette?
Dr. Cozette: When I think about the word swag, confidence comes to mind – determination, perseverance, and resilience! What makes me, me is “standing in my power and always operating in excellence; the thought of knowing that I hold myself to a high personal standard of integrity.â€
Fancy: So do you identify as a financial coach or an advisor and can you explain the difference between the two?
Dr. Cozette: I perform in both capacities. When working with business clients, I perform in the role of a financial advisor. However, when working with clients on personal financial matters, I assume the role of a financial coach.
Both roles are similar in nature, whereby financial advisors tend to focus on implementing financial products and strategies, while a financial coach will focus more on the basics of personal money management, behavioral change, and accountability to a client-driven spending plan.
Fancy: What’s your money story? Did your parents instill healthy money habits within you at an early age? Were finances discussed with you in your home?
Dr. Cozette: Every woman has a story where a door opened for them. My story was transitioning from Welfare to Warrior before I began winning at the game of work, life, and business! Before I could reach back and pay it forward to other women, I had to cleanse my mind and get rid of the limited mindset of what I called Welfare. Once I got into a safe space where I was able to cope, position, and leverage life, things got better for me. Now I’m winning! You can read my entire story of how I suffered through a marriage filled with domestic violence in my book “Unveiling the Mask†(available on Amazon.com).
Both of my parents were deceased, so money was not always discussed growing up. We had the basic conversations, that most of my peers did, but we were not privileged with learning how to invest and make our money grow for us.
Fancy: Can you describe what the process of working with you is like and why are you passionate about creating financial security for others?
Dr.Cozette: My organization, My Financial Home Enterprises, is dedicated to providing comprehensive accounting, tax and business management services for businesses. I ensure that we empower, educate, and equip our small business owners with the knowledge, tools, and strategies to build highly profitable 6- and 7-figure businesses and turn every day into a payday. As America’s #1 Advisory Accountant and Tax, I created the company after having numerous conversations with small business owners about the importance of designing a financial blueprint and seeing so many of my colleagues start businesses that failed.
Fancy: Can you share a few tips for choosing the right financial advisor and when might be the right time to hire one?
Dr. Cozette: Managing your own finances can be challenging — even overwhelming. A financial advisor may be able to provide the guidance you’re looking for to help achieve your long-term financial goals. But keep in mind: Not all financial professionals are alike.
A financial advisor can help you navigate the sometimes treacherous waters of money management and provide support on the journey toward your financial goals.
 But there are many types of financial professionals out there. “Financial advisor†is actually a general term that is often used to describe anyone in the business of helping others with their finances. A financial advisor might help with anything from general financial planning to investment management to tax and retirement strategy, and it can depend on their specialty.
Financial advisors may or may not have a variety of credentials, from educational backgrounds, professional experiences, and costs associated with their services. So before choosing a financial advisor, it’s a good idea to do some research. The research should help you –
-
Decide if you need a human financial advisor
-
Determine the type of advisor you want
-
Get referrals from friends or Google
-
Check the financial advisor’s credentials
-
Interview multiple advisors
Signs you might need a financial advisor
Over your lifetime, your financial plan and goals can evolve. Everything from making a career change to inheriting funds from a family member can have an impact on your financial life. When a big change happens, it can help to have someone by your side helping you make financial decisions.
Here are just a few reasons it might be time to think about looking into a financial advisor.
-
You’re just starting out –
-
You’re getting married
-
You’re entering midlife
-
Retirement is on the horizon
-
You want to stay retired
Bottom line
Partnering with a financial advisor could give you the guidance you need to help you achieve your short- and long-term financial goals, and may strengthen your overall financial well-being. However, not all professionals are the same. You need to do your homework before deciding on which professional to work with. It’s important to compare your options to find the right financial advisor for your needs.
Fancy: What’s the most important advice you can give to millennials and people who aren’t used to thinking about their finances? Â
Dr. Cozette: If you have to choose, tackle credit card debt before student loans – Focus on paying off your credit cards first, because that interest tends to be the higher yield; focus on any loan debt yielding over 6% to 7%, whether that’s student loans, car loans, or any other expensive debt.
Try to make the 50-30-20 rule your goal – put 50% of your take-home pay toward needs (bills, groceries, housing, transportation, etc.); 30% toward “wants†(aka the things that add joy to your life, like fun trips or happy hours with friends); and 20% toward “future you,†meaning savings, investments, and debt payments above minimums.
This may not always be possible, of course — life is expensive! — so if your needs currently exceed 50% of your take-home pay, think about the steps you might want to take or expenses you may be able to reduce in order to make this a more attainable plan.
Start investing your money right now — even if you can only invest a few dollars a week – A dollar in your twenties is worth more than a dollar in your thirties, forties, or fifties, thanks to the power of compounding. As long as the market rises, investment gains compound. In 10 years, an investment of $100 that grows at 4% annually will be worth $148; $1,000 becomes $1,480; $10,000 becomes $14,802, and so on. No amount is too little or too much — just start investing with whatever you can, whether that’s through your employer’s 401(k) or otherwise.
About that 401(k): Use it! And determine how much to contribute based on how much your company matches – Though retirement might seem ages away, as soon as you have the opportunity to invest in a 401(k), do it, regardless of how much money you’re making. There are two powerful wealth builders in a 401(k)! First off, its tax benefits; your money can build in a tax-deferred way. The second is, if your company has a match, that is free money…if you put in 10, and they put in 10, you have a 100% return immediately. And then the value grows off of double what you can afford to put in. If your company matches half of what you put in, you get a 50% return, and so forth.
A good rule of thumb is putting 10% into your 401(k), and then, aligning with the 50-30-20 rule, putting that other 10% for “future you†into savings or investments. And as you get older, you might want to consider switching those percentages around and investing more in your 401(k) and putting less in your savings — after, for instance, you’ve already bought the property you were saving up for all those years.
Aim to save at least three months’ worth of take-home pay in an emergency fund — a savings account stored in the bank – You may be wondering if “savings account†and the oft-referenced “emergency fund†are interchangeable terms, and they are indeed. Earlier in your career, you should aim to save at least three months of your take-home pay; as responsibilities and obligations accrue, six months of pay is ideal as you move further upward in your career.
Look for credit cards with the lowest interest rates – Cards that promise bonus points for travel and other perks can be enticing, but low-interest rates are the most crucial factor if you aren’t the rare unicorn paying off your credit cards in full every single month.
If your credit score isn’t nearly where you want it to be, don’t panic – First off, you can (and should!) regularly check your credit score for free on a site like Credit Karma. Monitoring your own credit is what’s called a “soft†check — it won’t affect your score, unlike a “hard check†(i.e., when a potential lender reviews your credit for a loan, mortgage, or credit card).
While a “good†credit score is generally considered to be 700-749 and an “excellent†one 750+, if that range seems miles away, just take a deep breath and do what you can. Don’t cry over spilled milk. If you’re there, you’re there, so just pay your debt on time, work down that credit card debt to the best of your ability, pay those student loans, and just one foot in front of the other and don’t make the same mistakes again. Just because you made them in your twenties doesn’t mean you have to make them in your thirties — even if your twenties were more fun!
Now go forth with your newfound financial wisdom and prosper. You’ve got this!
Fancy: You have a book as well. Can you share a little about it?
Dr. Cozette: During Women’s History Month, I became the first African-American Woman to debut five personal and business finances books in one day – three of which became Amazon bestsellers. I wrote five books because “starting your own business can be a very rewarding venture, but where do you begin with more than 5,000,000 new businesses starting each year yet 70% of them fail. So, I wrote the books to aid new entrepreneurs.â€
In addition, I have Unveiling the Mask – A guide to recovering after a financial disaster and Attracting the Best – Wealth, Prosperity and Abundance. All books are available on Amazon.com
Fancy: Do you have any upcoming events or projects you care to share?
Dr. Cozette: I am a resident Money Matter’s Expert for FOX40. I can be seen sharing expert advice on most money matters every month.
Dr. Cozette received her Master of Business Administration degree from the University of La Verne and her Bachelor of Science degree in Accounting from California State University, Dominguez Hills. Later, Dr. Cozette was awarded a Doctorate Degree of Philosophy Letters. She is involved in her community and is a member of Alpha Kappa Alpha Sorority, Inc.; she is a member of the National Association of Black Accountants and National Black MBA Association.
Connect with Dr. Cozette below. Â
-
Websites : www.cozettemwhite.com and www.myfinancialhome.com
-
LinkedIn: https://www.linkedin.com/in/cozettemwhite/Â
-
Instagram: @cozettemwhite
Also, look for Dr. Cozette in our Unapologetic Issue.Â